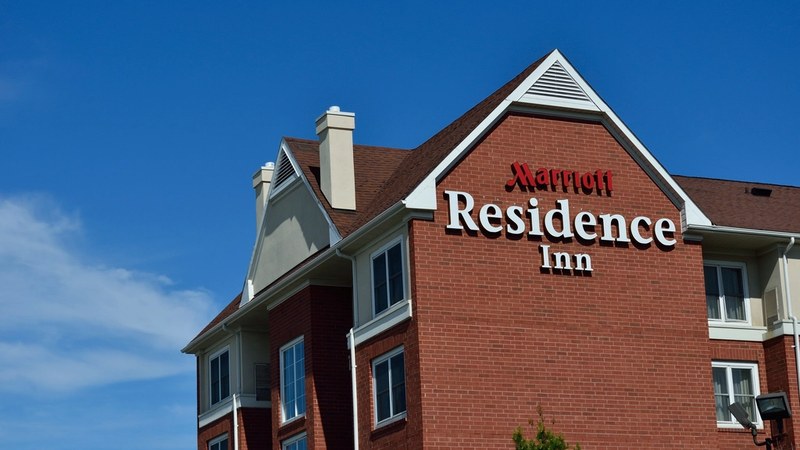
Marriott International experienced stronger-than-expected operating momentum in the third quarter of 2026, leading the company to raise its full-year revenue per available room (RevPAR) growth outlook to between 4.5% and 5%, up from the previous range of 3% to 3.5%. Global RevPAR increased 6.5% year over year in Q3, with the United States and Canada posting a 7.4% gain and international markets rising 4.4%. In the Asia-Pacific Economic Cooperation (APEC) region, RevPAR growth exceeded 9%, despite ongoing challenges in the Middle East, where trends improved significantly compared to the prior quarter.
Q3 Financial Performance and Earnings
Franchise and base management fees grew 13% to $1.341
billion in Q3 2026, while incentive management fees increased 22% to $181 million. Gross fee revenue rose 14% year over year, reaching $1.52 billion. Marriott’s reported net income advanced 9% to $794 million from $728 million in Q3 2025. Reported diluted earnings per share topped $3.04, compared with $2.67 in the previous year. Adjusted diluted earnings per share increased to $3.02 from $2.47, and adjusted EBITDA climbed 12% to $1.512 billion, excluding cost reimbursement revenue, reimbursed expenses, and certain impairment charges.
Room Expansion and Loyalty Membership
During Q3 2026, Marriott added approximately 20,100 net rooms, with over 13,400 located outside the United States and Canada.
Its development pipeline comprises 4,209 properties, totaling more than 634,000 rooms, with more than 50% of these rooms situated internationally. Marriott Bonvoy membership reached roughly 309 million at the close of the quarter. The company repurchased 3.5 million shares for $1.3 billion during Q3 and returned about $4 billion to shareholders through dividends and buybacks through October 28, 2026. On November 9, Marriott’s shares traded at 374.60 euros on Lang & Schwarz market at 13:41:31 Central European Time.
CEO Commentary on Demand and Regional Performance
Marriott’s chief executive credited the company’s global scale, brand portfolio, and revenue management capabilities for the quarter’s performance. He emphasized robust international
demand, particularly in the APEC region, where RevPAR growth exceeded 9%. Although the Middle East continued to hinder overall results, the area showed marked improvement compared to the second quarter of 2026.
Business Model and Market Context
Marriott’s asset-light fee-based business model remains a key driver of earnings growth. The company’s operating momentum has been supported by higher room rates and occupancy across its system. While fee growth, room additions, and share repurchases contribute to the positive earnings outlook, ongoing hotel demand levels and regional geopolitical risks continue to be critical factors for investors evaluating Marriott stock. Broader market trends are also relevant to hotel
share performance, providing important context for the company’s financial results.